What Metrics Should a Small Business Track?

On this page
Analytics & Data
It is Monday morning. You run a hypothetical 25-person company and have roughly 40 numbers open across GA4, your ad platform, the CRM, and Stripe or your accounting tool. Three need a decision, and the rest are competing for your attention.
What metrics should a small business track? Pick 3 to 5 by business model and current constraint, with a source, formula, and threshold written down before you look. Start with break-even cost per lead: $600 gross margin per job multiplied by a 30% close rate gives you $180.
Notice how the four remaining numbers each have a decision attached. A dashboard can retain other data without putting every number on Monday's agenda.
Choose a business model, then the constraint
Pick the model closest to how you earn revenue. Then pick the constraint that currently limits the business. If the lists conflict, the constraint takes priority: a service company short of cash may need payback and receivables on Monday more than another view of booked jobs.
For each selected metric, write down an owner, the source system, the formula, and the value that will trigger an action before opening the report. A number for which no possible value would change an action is decoration. The small business analytics guide has the fuller definitions, a source-of-truth map, and the sample-size arithmetic.
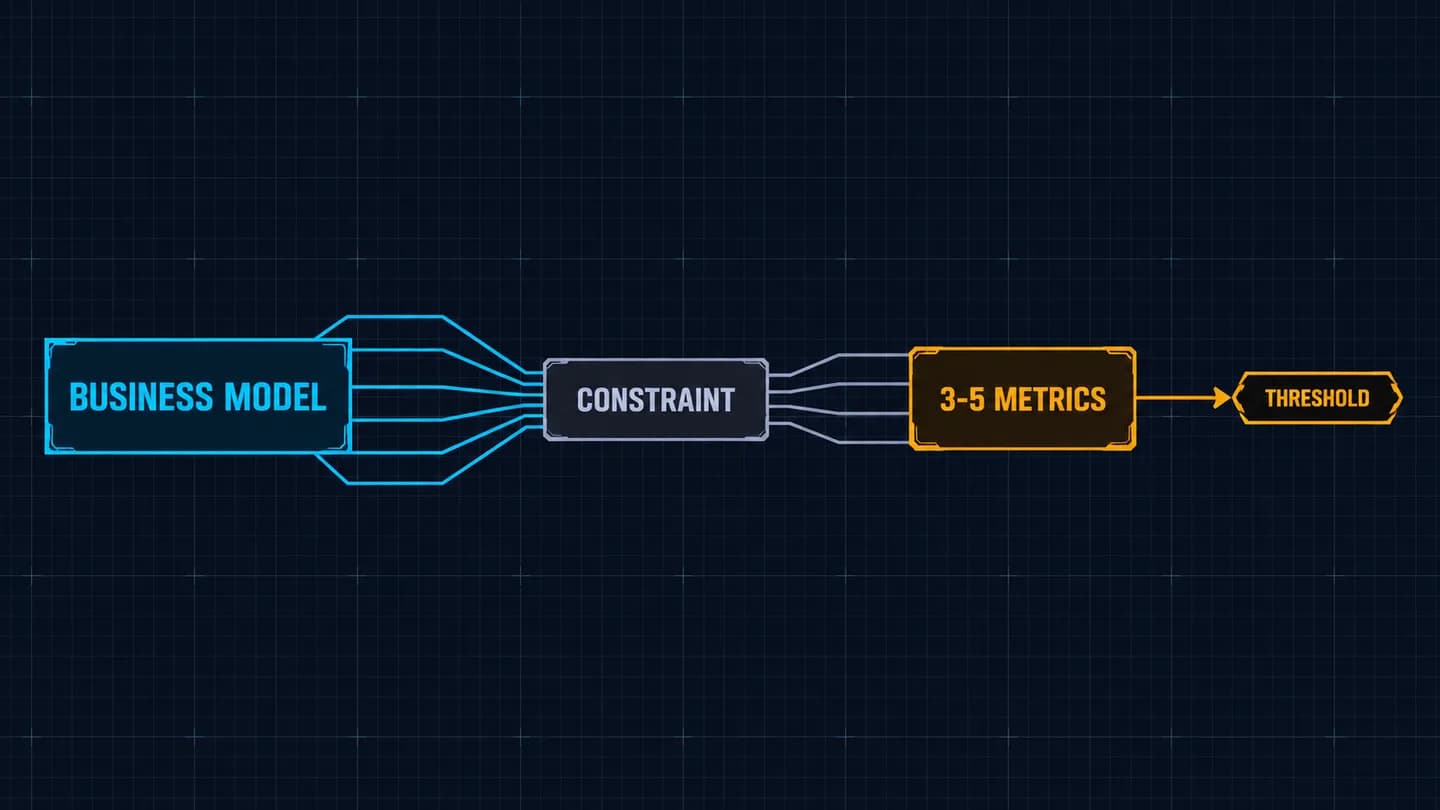
Choose the business model first and the current constraint second. The resulting metric list needs an action threshold for each number.
The formulas below use consistent definitions across the branches. Channel spend and the leads or customers it produced need to refer to the same channel and a comparable acquisition period.
CPL = channel spend / leads CAC = channel spend / new customers payback months = CAC / monthly gross margin per customer break-even cost per lead = gross margin per customer x close rate customers = leads x close rate subscriber churn = subscribers churned in the last 30 days / (active subscribers 30 days ago + new subscribers in the last 30 days) ARPU = total MRR / active subscribers revenue LTV = ARPU / subscriber churn rate margin LTV = revenue LTV x gross margin rate DSO = accounts receivable / revenue in the period x days in the period
For a job or order, calculate gross margin after the direct cost of fulfillment. In the hypothetical $600 job example, the 30% close rate means $180 per lead is the first-sale break-even point, before other business costs. The paid acquisition arithmetic shows how to use that limit in a paid test.
Stripe, Recurly, Baymard, and Google documentation was read on 29 October 2026.
Moves inside the square-root band are not triggers under our rule of thumb. A count of 16 leads has a typical swing of about 4, so 12 or 20 can be ordinary variation.
For a hypothetical page with 3 leads from 100 visits, the observed rate is 3%, with a rough 95% interval of about 0% to 6.4%. A move from 2% to 4% on 100 visits in each period tells you nothing yet. Use rolling 12-week figures for budget decisions where possible, and check weekly for broken tracking or missed follow-up.
Choose metrics by business model
If you sell local services, track jobs and the path to booking
If you sell jobs to nearby customers, use the CRM or job log as the count of record for booked work. The thresholds in this branch are our rules of thumb: write your own job target and close-rate review threshold before looking, then apply the break-even rule to paid leads.
- Booked jobs: In the CRM or job log, count jobs booked in the period. If the count falls below your written capacity or sales plan outside the noise band, inspect lead volume and follow-up.
- Business Profile calls: In Google Business Profile Performance, Google counts Calls as clicks on the profile's call button; a phone number must be on the profile. If clicks fall against your trailing baseline while booked jobs also fall, check the profile and its phone number. Our reading of Google's performance documentation is that a click is not an answered call or a booked job, so those need separate records.
- CPL against break-even CPL: Divide channel spend by leads, using ad-platform spend and CRM leads. If CPL exceeds gross margin per job multiplied by close rate for two consecutive months on at least about 20 leads, fix or cut the channel.
- Close rate: In the CRM, divide new customers by leads in the cohort, grouped by the month the leads arrived. If it crosses your written review threshold, inspect the source and follow-up records before changing spend.
A cheap lead can still be expensive if few leads become customers. Keep the close rate tied to a lead cohort so a job won later is credited to the month that produced the inquiry.
If you generate B2B leads, track qualification through payback
If your sales process has several stages, track leads from their arrival month through a won deal. These thresholds are our rules of thumb: use your sales plan and cash position to set the values for qualification and cycle time, and use the stated comparison for source close rates.
- Qualified leads: In the CRM, count leads meeting your written qualification criteria. If the weekly count falls below plan outside the noise band, inspect source capture and the criteria before buying more traffic.
- Lead-to-customer close rate: Divide customers won from a lead cohort by all leads in that cohort. If a source closes at less than half the overall rate across at least 30 leads, fix qualification or follow-up before increasing its budget.
- Sales cycle days: In the CRM, calculate days from lead creation to deal won. If the cycle exceeds your written planning assumption, inspect stalled stages and update the cash forecast.
- CAC: Divide channel spend by new customers from that channel. If CAC exceeds the gross margin from the first sale and your plan relies on first-sale recovery, fix the channel economics.
- CAC payback: Divide CAC by monthly gross margin per customer, using CRM acquisition records and accounting margin. If payback exceeds the months of cash you hold, stop scaling acquisition until it shortens.
Forms and events need to capture a source into the CRM for the qualified-lead count by source to be useful. Foundation is relevant when those fields and events need to be built into the site.
Ad platforms can claim overlapping conversions. Keep the CRM as the lead count of record; GA4 data-driven attribution distributes credit for a key event, which is a different job from counting distinct leads or proving what caused them.
If you sell through an ecommerce store, track order economics and repeat buying
If customers place orders online, use store analytics and order records to connect conversion to margin. These thresholds are our rules of thumb: set your own review points from your plan and trailing baseline, and use first-order gross margin as the break-even limit when the first order must recover acquisition cost.
- Conversion rate: Divide orders by sessions in store analytics. If a sustained change crosses your written baseline threshold and the sample is large enough to interpret, inspect the affected pages and checkout.
- Average order value: Divide revenue by orders in the store platform. If it falls below your planning assumption, check order mix and its effect on gross margin.
- First-order gross margin against CPA: Subtract direct fulfillment costs from first-order revenue, then compare that margin with acquisition cost per new customer. If CPA exceeds first-order margin and you require first-order recovery, fix or pause acquisition.
- Repeat purchase rate: Divide customers with two or more orders by customers in the period, using customer order records. If the rate falls below the assumption used to justify acquisition spending, revise that assumption and the budget.
If you count expected repeat margin in your acquisition limit, write that expectation down and check whether customers actually return. Do not spend projected repeat margin twice.
Baymard's cart abandonment research reports a 70.22% average across 50 studies, with the page last updated on 22 September 2025. Our inference is that a result near 70% alone is not a trigger; a jump against your own trailing baseline is a reason to investigate.
If you sell subscriptions or SaaS, track margin and the cause of churn
If customers pay repeatedly, use subscription records to follow recurring revenue and subscriber losses. These thresholds are our rules of thumb: compare results with your written operating assumptions, investigate failed-payment recovery when involuntary churn reaches a third of total churn, and compare CAC with margin LTV.
- MRR: In Stripe Billing analytics, sum the monthly-normalized value of subscriptions in
activeandpast_duestatus. If MRR falls below your written plan, inspect new subscriptions and churn. Stripe excludes taxes, free plans, and usage-based products from this measure. - Subscriber churn: Divide subscribers churned in the last 30 days by active subscribers 30 days ago plus new subscribers in the last 30 days. If the rate exceeds your written retention assumption, separate voluntary and involuntary losses.
- ARPU: Divide total MRR by active subscribers in Stripe. If ARPU falls below the assumption used in your customer economics, inspect plan and customer mix.
- Margin LTV against CAC: Divide ARPU by subscriber churn rate for estimated revenue LTV, then multiply by the gross margin rate. If CAC exceeds that margin estimate, revisit acquisition economics and the assumptions behind it.
- Involuntary share of churn: Divide subscribers lost to failed payments by total churned subscribers, using billing records. If the share is a third or more, fix payment retries and update reminders before prioritizing save offers.
Stripe's Billing analytics documentation gives a churn example of 100 / (1,000 + 100), or 9.1%. Its subscriber LTV is an estimate. For a hypothetical $50,000 MRR and 100 active subscribers, ARPU is $500; at 9% churn, revenue LTV is about $5,555. At an assumed 40% gross margin, margin LTV is about $2,222. The revenue estimate is before gross margin, so it is not profit.
Recurly's churn benchmarks use July 2026 figures from its network and do not state a sample size. Our calculation of its SaaS figures, 1.06 / 3.22, puts involuntary churn at about one third of total churn. A share near Recurly's median already meets our rule of thumb, so failed-payment recovery is a common first fix. That split is a prompt to inspect your own records, not a target or a verdict on whether a churn rate is good.
If you run an agency or professional service, track capacity and cash exposure
If revenue depends on people's time, connect hours to fee revenue and watch how much income depends on one customer. These thresholds are our rules of thumb: use your staffing and cash plans for utilization, hourly rate, and DSO; put new-business pipeline on the weekly list when one client exceeds about 25% of revenue.
- Utilization: Divide billable hours by available hours in your time-tracking system. If it crosses the threshold in your staffing plan, review capacity and the work scheduled.
- Effective hourly rate: Divide fee revenue by total hours spent on a client, combining accounting and time records. If it falls below the rate assumed in the engagement plan, review scope and pricing.
- Client concentration: Divide the largest client's revenue by total revenue in accounting. If it exceeds about 25%, put new-business pipeline on the weekly list.
- DSO: Divide accounts receivable by revenue in the period and multiply by days in the period. If DSO exceeds the collection assumption in your cash plan, review overdue invoices and follow-up.
Available hours need a consistent definition in your time system. A change in that definition can move utilization even when the amount of billable work has not changed.
Choose metrics by current constraint
If you do not have enough leads, find the source and cost of the shortfall
If the pipeline needs more inquiries, count leads by source in the CRM and compare their cost with the margin they can produce. These thresholds are our rules of thumb: use your written weekly lead plan, the two-month break-even test, and a preselected conversion review threshold.
- Leads per week by source: Count CRM leads by captured source and arrival week. If a source falls below plan outside the noise band, check capture and delivery before changing the budget.
- CPL against break-even: Divide channel spend by CRM leads, then compare it with gross margin per customer multiplied by close rate. If CPL stays above break-even for two consecutive months on at least about 20 leads, fix or cut the channel.
- Landing-page conversion: Divide leads from the page by visits to it, using a consistent page and event definition. If the rate crosses your written threshold on a sufficiently informative sample, inspect the page and form.
- Close rate by source: Divide customers by leads from the same source and arrival cohort. If a source falls below half the overall close rate across at least 30 leads, fix qualification or follow-up before buying more.
Three leads from 100 visits give an observed 3% conversion rate, but the rough interval is about 0% to 6.4%. That uncertainty is too wide to treat a small change on another 100 visits as proof that a page edit worked.
If leads arrive but few close, inspect source quality and response
If inquiries are reaching the CRM but sales are weak, inspect the path from arrival to a first reply and then to a won deal. These thresholds are our rules of thumb: use the half-the-overall-rate test for a source, and write response and qualification thresholds that fit your sales process before reviewing them.
- Close rate by source: Divide customers won by leads in each source's arrival cohort. If a source is below half the overall close rate across at least 30 leads, fix qualification or follow-up before buying more.
- Speed to first response: In the CRM, calculate time from lead creation to the first logged reply. If it exceeds your written response standard, review the queue and assignment process.
- Qualified share: Divide qualified leads by all leads in the same cohort, using documented CRM qualification criteria. If the share falls below your planning assumption, inspect the source and qualification process.
- Sales cycle days: Calculate days from lead creation to deal won using CRM timestamps. If it exceeds the assumption in your sales plan, review stalled stages and update the forecast.
A response-time number is only as useful as the reply logging behind it. Give one person responsibility for checking that replies and stage changes are recorded consistently.
If customers churn, separate cancellations from payment failures
If subscribers are leaving, measure losses by cohort and identify which ones failed to renew because payment failed. These thresholds are our rules of thumb: use your written retention assumption and fix payment recovery first when involuntary churn reaches a third of total churn.
- Subscriber churn: Use the Stripe 30-day formula in the shared formula block. If churn exceeds your written assumption, inspect cancellations and failed renewals separately.
- Cohort retention: Divide subscribers still active at each interval by the starting subscribers in that cohort. If retention falls below the assumption used in your plan, inspect the interval and reason for loss.
- Involuntary share: Divide churned subscribers lost to failed payments by total churned subscribers. If it is a third or more, review card retries and payment-update reminders first.
- Margin LTV against CAC: Compare estimated revenue LTV multiplied by gross margin rate with CAC. If CAC exceeds the margin estimate, revisit acquisition spending and the churn assumption.
For a hypothetical cohort with 10% churn each month and no returning subscribers, retention is 90%, 81%, 73%, 66%, and 59% after months one through five. The compounding makes a recurring loss visible in a way a single month's count can hide.
If cash is tight, compare acquisition recovery with the cash available
If cash is the immediate constraint, put acquisition payback and collection time beside the cash forecast. These thresholds are our rules of thumb: stop scaling when payback exceeds the months of cash you hold, and use your written collection and gross-margin assumptions for the other decisions.
- CAC payback: Divide CAC by monthly gross margin per customer, using channel spend, new customers, and accounting margin. If payback is longer than the months of cash you hold, stop scaling acquisition until it shortens.
- DSO: Divide accounts receivable by period revenue and multiply by days in the period. If DSO exceeds the assumption in your cash plan, review overdue invoices and collection follow-up.
- Gross margin: Subtract direct fulfillment costs from revenue, then divide by revenue for the margin rate. If the rate falls below the assumption in your cash plan, inspect direct costs and pricing.
- Cash held in months: Divide cash available by the monthly cash outflow assumed in your forecast. If that runway falls below CAC payback, pause acquisition scaling and update the forecast.
For a hypothetical acquisition, $400 CAC divided by $100 monthly gross margin per customer gives four months of payback. For a separate hypothetical receivables calculation, $60,000 outstanding divided by $90,000 revenue over 90 days, multiplied by 90, gives 60 days of DSO. Compare each result with your own cash plan; neither number is a universal target.
Choose the metric list for your situation
| Situation | Metrics | Where they live | Action threshold |
|---|---|---|---|
| Local service | Booked jobs, call-button clicks, CPL, close rate | CRM or job log, Business Profile, ad platform | CPL above break-even for two months on at least about 20 leads: fix or cut the channel. |
| Lead-gen B2B | Qualified leads, close rate, sales cycle, CAC, payback | CRM, ad platform, accounting | Source close rate below half overall across at least 30 leads: fix qualification or follow-up. |
| Ecommerce | Conversion rate, average order value, first-order margin versus CPA, repeat purchase rate | Store analytics, order records, ad platform | CPA above first-order margin when first-sale recovery is required: fix or pause acquisition. |
| Subscription or SaaS | MRR, subscriber churn, ARPU, margin LTV versus CAC, involuntary share | Stripe or billing system, accounting, acquisition records | Involuntary churn at a third or more of total churn: fix payment recovery first. |
| Agency or professional services | Utilization, effective hourly rate, client concentration, DSO | Time tracking, accounting | One client above about 25% of revenue: put new-business pipeline on the weekly list. |
| Not enough leads | Leads by source, CPL, landing-page conversion, close rate by source | CRM, ad platform, site analytics | CPL above break-even for two months on at least about 20 leads: fix or cut the channel. |
| Leads but low close rate | Close rate by source, first-response time, qualified share, sales cycle | CRM | Source close rate below half overall across at least 30 leads: fix qualification or follow-up. |
| Customers churn | Subscriber churn, cohort retention, involuntary share, margin LTV versus CAC | Billing system, accounting, acquisition records | Involuntary churn at a third or more of total churn: fix payment recovery first. |
| Cash tight | CAC payback, DSO, gross margin, cash held in months | Accounting, CRM, ad platform, cash forecast | Payback longer than cash held in months: stop scaling acquisition. |
Write the chosen metrics, owners, sources, and thresholds into a measurement plan before the next review. Use KPIs and targets that drive action to turn each threshold into a target with an owner.

Put your next steps in order
Build on what you have just read with a free ebook on semantic SEO and AI visibility. Get worked examples, decision rules, checklists and a do-this-week action in every chapter, plus a six-week plan for your site.