Small Business Cash Flow Management

On this page
- Stage 1: The profitable quarter that drained cash
- Stage 2: The 13-week forecast exposes the low week
- Stage 3: Days cash, DSO and the cash conversion cycle
- Stage 4: Collect deposits and invoice when work closes
- Stage 5: Pay suppliers on agreed terms and audit subscriptions
- Stage 6: Set a cash reserve and arrange a backstop
- Stage 7: The fixed forecast and funded reserve
- A weekly cash review with observable checks
Business
The median small business held 27 cash buffer days in a JPMorgan Chase Institute study. Small business cash flow management means knowing, week by week, whether cash in the bank covers what leaves, and moving the timing of money in and out so it does. A profitable quarter can still end with a bank balance too small for the next payroll.
The JPMorgan Chase Institute study, published in September 2016, examined 597,000 small businesses and transactions from February through October 2015. Its cash buffer measure divided average daily cash balance by average daily cash outflows. A quarter held fewer than 13 buffer days, a quarter held over 62, and the medians for construction and restaurants were 20 and 16 days respectively.
These are data from 2015 and from one bank's customers, not a census or a reserve prescription. They are useful context for a question that stays with the owner even as tools and markets change: what running a business means in the AI era.
Fernhollow Landscaping is fictional, and every Fernhollow number in the tables and text is an assumption of the example. The company has commercial and residential customers, design-build installations, maintenance contracts and a spring-to-autumn season. Its starting inputs make the timing problem concrete.
| Assumed input | Fernhollow value |
|---|---|
| Staff | 16 |
| Annual revenue | $2,400,000 |
| Net margin | 8% |
| Annual cash operating expenses | $2,160,000 |
| Cash operating expenses per day | $5,918 |
| Annual materials purchases | $600,000 |
| Q2 revenue | $720,000 |
The daily expense figure is $2,160,000 divided by 365, rounded for display. It excludes noncash expenses such as depreciation. The company can earn an acceptable margin and still need financing for the weeks between buying materials and collecting payment.
Stage 1: The profitable quarter that drained cash
Fernhollow's assumed second-quarter profit was $61,000, yet its cash balance fell by $104,000. The bridge tracks the changes between April 1 and June 30. Positive amounts add cash; negative amounts use it.
| Line | Amount |
|---|---|
| Opening cash 1 April | $142,000 |
| Net profit for the quarter | +$61,000 |
| Add back depreciation (non-cash) | +$9,000 |
| Receivables up from $338,000 to $464,000 | -$126,000 |
| Materials on hand up | -$8,000 |
| Equipment loan principal (not on the P&L) | -$18,000 |
| Owner draws | -$22,000 |
| Closing cash 30 June | $38,000 |
Receivables grew because Fernhollow sent invoices in a monthly batch, about 15 days after completion on average. Commercial invoices had net 30 terms, and customers actually paid later. The company also took no deposits on installations, bought materials up front and paid suppliers in about 15 days.
Loan principal and owner draws never appear on the profit and loss statement, yet both take money out of the bank. Growing receivables also consume cash during a busy season: revenue can be recorded before the customer pays.
The bridge is a reconciliation, not a list of expenses to cut. Depreciation is added back because it reduced accounting profit without taking cash during the quarter. The increase in receivables is subtracted because the assumed revenue includes work for which the cash has not arrived.
An owner should also check whether each job earns enough before treating timing as the whole problem. The separate calculation for pricing and unit economics shows what a job earns underneath its payment schedule. Faster collection cannot turn an unprofitable installation into a profitable one.
Stage 2: The 13-week forecast exposes the low week
A 13-week cash flow forecast uses the direct method: put expected cash receipts and disbursements in the weeks when they should reach or leave the bank. Start week 1 with today's bank balance. For receipts, use the accounts receivable aging and expected billings, placing each payment on its expected pay date, not the invoice date.
Put payroll, supplier payments, rent, loan payments and other outflows in the weeks cash is due to leave. Subtract disbursements from receipts to get net cash movement, then add net to opening cash. Each closing balance becomes the next week's opening balance.
The table assumes Fernhollow starts its July to September forecast with $38,000. Payroll is $46,000 every other week. Other out includes rent, equipment loan payments, insurance, software and owner draws.
| Week | Opening | Receipts | Payroll | Materials | Other out | Net | Closing |
|---|---|---|---|---|---|---|---|
| 1 | 38,000 | 41,000 | 46,000 | 14,000 | 6,000 | -25,000 | 13,000 |
| 2 | 13,000 | 38,000 | 0 | 12,000 | 22,000 | 4,000 | 17,000 |
| 3 | 17,000 | 44,000 | 46,000 | 13,000 | 5,000 | -20,000 | -3,000 |
| 4 | -3,000 | 36,000 | 0 | 12,000 | 6,000 | 18,000 | 15,000 |
| 5 | 15,000 | 40,000 | 46,000 | 12,000 | 24,000 | -42,000 | -27,000 |
| 6 | -27,000 | 35,000 | 0 | 11,000 | 5,000 | 19,000 | -8,000 |
| 7 | -8,000 | 47,000 | 46,000 | 12,000 | 6,000 | -17,000 | -25,000 |
| 8 | -25,000 | 52,000 | 0 | 12,000 | 22,000 | 18,000 | -7,000 |
| 9 | -7,000 | 50,000 | 46,000 | 11,000 | 5,000 | -12,000 | -19,000 |
| 10 | -19,000 | 55,000 | 0 | 11,000 | 6,000 | 38,000 | 19,000 |
| 11 | 19,000 | 54,000 | 46,000 | 10,000 | 22,000 | -24,000 | -5,000 |
| 12 | -5,000 | 58,000 | 0 | 10,000 | 5,000 | 43,000 | 38,000 |
| 13 | 38,000 | 56,000 | 46,000 | 9,000 | 6,000 | -5,000 | 33,000 |
The assumed low point is week 5, at -$27,000, when payroll and heavier month-start bills fall together. Seven of the 13 weeks close below zero even though the company is profitable. A negative balance is a financing gap in the model: the bank will not quietly accept a negative forecast as a payment plan.
For a seasonal business, build the receipts line from the actual customer mix and expected payment dates for that season. A busy sales calendar can increase the need for cash before it increases the bank balance, especially when materials and labor come due before customers pay. Keep the larger bills visible by week so a profitable month does not hide an unfunded payroll.
The owner and office manager review the weekly forecast together, looking for the lowest closing balance before that week arrives.
Every week, record actual receipts and payments beside the forecast and compare the difference line by line. Correct the expected dates and amounts for the remaining weeks, drop the completed week and add a new week 13. The forecast remains a rolling 13-week view rather than a document that expires after one review.
Stage 3: Days cash, DSO and the cash conversion cycle
Three measures describe different parts of Fernhollow's assumed position. Days cash on hand asks how much operating cash is available; days sales outstanding, or DSO, estimates the collection time represented by receivables; the cash conversion cycle combines inventory, collections and supplier payment timing.
The DSO calculation uses an assumed 90-day quarter.
days cash on hand = cash / (annual cash operating expenses / 365) = $38,000 / ($2,160,000 / 365) = 6.4 days
DSO = accounts receivable / revenue in the period x days in the period = $464,000 / $720,000 x 90 = 58 days
cash conversion cycle = DIO + DSO - DPO = 12 + 58 - 15 = 55 days
| Assumed measure | Value | Question it answers |
|---|---|---|
| Days cash on hand | 6.4 days | How many days of cash operating expenses can the current balance cover? |
| DSO | 58 days | How much collection time is represented by receivables relative to the quarter's revenue? |
| Cash conversion cycle | 55 days | How long is cash tied up across inventory and collections after allowing for supplier payment time? |
Use the same period's revenue and days when calculating DSO. Fernhollow's example uses $464,000 in receivables, $720,000 in second-quarter revenue and 90 days. A seasonal company using annual revenue at a seasonal peak can get a misleading result because its sales rate changes through the year.
DSO is an indicator, not a promise that every invoice will be paid in 58 days. Compare the calculation with the collection dates assumed in the cash forecast and investigate the invoices that make those dates doubtful. The wider set of business metrics includes that comparison between DSO and the collection assumption in a cash plan.
DIO means days inventory outstanding, and DPO means days payables outstanding. In the assumed cycle, materials remain on hand for 12 days, receivables represent 58 days, and suppliers are paid in 15 days. The resulting 55 days is a timing measure; the weekly forecast still shows which particular bills and receipts create the trough.
Fernhollow's 6.4 days can be compared with the JPMorgan study's 27-day overall median and 20-day construction median. Those are 2015 medians across the study's industries, with construction reported separately, not targets for Fernhollow. JPMorgan also used average daily balance and all daily outflows, while this example uses a point-in-time balance and annual cash operating expenses.
Stage 4: Collect deposits and invoice when work closes
The assumed receivables changes start at the sale and continue through payment. Fernhollow asks for a 30% deposit on design-build installations at signing, issues the final invoice when the job is marked complete and uses net 15 terms on installations. Maintenance is billed on the first of the month, due on the 15th, by ACH autopay.
| Assumed change | Timing it addresses | Observable check |
|---|---|---|
| 30% install deposit | Cash for materials arrives earlier | The signed job has a deposit invoice and recorded payment |
| Invoice on completion | The monthly billing delay disappears | The completed job has an invoice dated that day |
| Net 15 install terms | The agreed payment date moves closer | The invoice displays its due date |
| Maintenance ACH autopay | Recurring bills have a scheduled collection method | The account has authorization and a scheduled payment |
| ACH-first pay link | Customers can choose a bank payment from the invoice | The payment link opens and offers ACH |
A deposit changes cash timing, so specify it in the customer's agreement and match it to the job's expected material costs. It is not extra revenue. The remaining invoice should reflect the deposit already paid, and its due date should be visible to both the customer and the person maintaining the forecast.
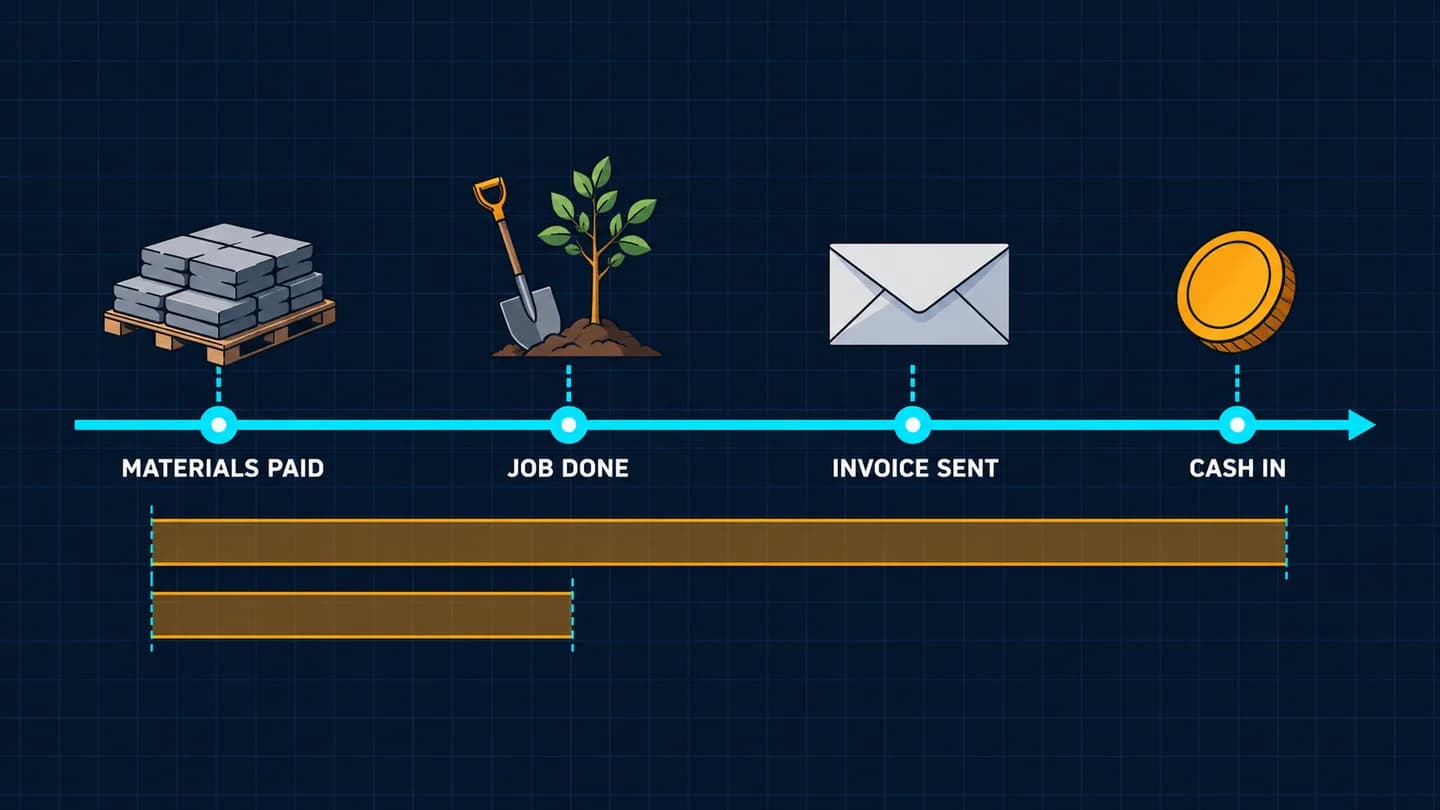
Notice the gap between paying for materials and collecting the invoice. A deposit brings some cash forward, while invoicing on completion removes the wait for the monthly batch.
The completion event can trigger an invoice and payment reminders, with someone checking exceptions such as missing customer details or a disputed job. Iron Goo's operations service follows an audit, build and operate model for an agentic operations layer for internal ops work, with monthly reports on what changed. The useful operational check is whether every completed job has a valid invoice and an expected payment date in the aging report.
ACH and card fees on a $6,000 invoice
Fernhollow's assumed invoice amount is $6,000. Stripe is the price example, and the figures are US standard pricing read on October 30, 2026. Other processors and pricing arrangements can differ.
| Payment or invoicing charge | Calculation | Fee on $6,000 |
|---|---|---|
| Stripe standard card payment | 2.9% x $6,000 + $0.30 | $174.30 |
| Stripe ACH Direct Debit | 0.8% x $6,000, capped at $5.00 | $5.00 |
| Stripe Invoicing Starter, if used | 0.4% x $6,000, on top of either payment fee | $24.00 |
At 0.8%, the Stripe ACH Direct Debit cap is reached at $625: $5 divided by 0.008. ACH settlement can take up to four business days, so the forecast should use the expected settlement date. Financial Connections verification costs $1.50 if used.
The card figure uses Stripe's standard card rate. Stripe Invoicing Starter adds its fee to the payment processing charge if Fernhollow uses that product. On the assumed invoice, the combined amount is $29.00 for capped ACH plus Starter, or $198.30 for the standard card charge plus Starter, before any applicable verification charge.
ACH first gives a customer a lower-fee option on a large invoice while preserving card as a choice. A card can still be useful for a smaller residential job paid on the spot. Whichever method the customer selects, update the forecast for the date the money is expected in the bank, which can be days after the customer starts the payment.
The assumed result of the receivables changes is DSO falling from 58 to 36 days. At the assumed $720,000 quarterly revenue rate, the calculation is (58 - 36) / 90 x $720,000 = $176,000 released from receivables. The forecast places that amount over weeks 3 through 13, or $16,000 per week; it is an assumption to test against actual collections, not a guaranteed result of changing terms.
Stage 5: Pay suppliers on agreed terms and audit subscriptions
Fernhollow's assumed supplier invoices already allow 30 days, but the company pays in about 15. Paying on the agreed due dates moves assumed DPO from 15 to 30 days without requiring a new term. The owner should confirm each invoice's due date and schedule payment accordingly.
| Assumed payables input | Calculation or result |
|---|---|
| Annual materials purchases | $600,000 |
| Materials per day | $600,000 / 365, about $1,644 |
| Change in payment timing | 15 days (30 days less 15 days) |
| One-time cash release | 15 x approximately $1,644 = about $24,658 |
| Amount placed in weeks 1 and 2 of the forecast | $24,000 |
This is a one-time timing release, not a permanent reduction in the cost of materials. Supplier bills still have to be paid. The after forecast assumes $12,000 less in material payments in each of the first two weeks; future forecasts must retain the actual due dates for the shifted bills.
The subscription audit is smaller, but the charges are observable and recurring. The unnamed vendor lines are hypothetical.
| Assumed subscription change | Monthly before | Monthly after | Monthly saving |
|---|---|---|---|
| ChatGPT Business, six Standard seats reduced to four | $150 | $100 | $50 |
| Unused second estimating tool | $179 | $0 | $179 |
| Duplicate cloud storage | $39 | $0 | $39 |
| Lapsed scheduling app | $67.50 | $0 | $67.50 |
| Total | $435.50 | $100 | $335.50 |
The assumed saving is $335.50 a month, or about $4,026 a year. The OpenAI help center reports ChatGPT Business Standard seats at $25 per user per month when billed monthly and $20 per user per month when billed annually. Check the actual seat list and renewal terms before removing access.
Fernhollow keeps its assumed Zapier 10,000-task tier on monthly billing at $193.50 because it runs the invoice-on-completion automation. Annual billing is reported at $129 per month, a $64.50 monthly saving, but requires $1,548 up front for the year. The lower monthly price pulls cash forward, so the example defers that decision until the reserve is funded.
Annual subscription savings are about 2% of the assumed $176,000 receivables release. That comparison does not make recurring savings worthless; it puts the work in order when an owner has a cash shortage. For a fuller cost estimate, price the AI automation line by line, including the platform and review work.
Stage 6: Set a cash reserve and arrange a backstop
Iron Goo's rule of thumb for a seasonal firm is to hold 30 days of cash operating expenses in cash and keep the lowest closing balance in the rolling 13-week forecast above zero without drawing a credit line. This is our opinion, not a standard. The commonly offered three to six months of expenses can be a useful prompt, but it does not account for a particular company's forecast trough or seasonality on its own.
| Assumed Fernhollow reserve input | Calculation or target |
|---|---|
| Annual cash operating expenses | $2,160,000 |
| Daily cash operating expenses | $2,160,000 / 365, about $5,918 |
| Cash reserve | 30 x unrounded daily expense = $177,534, about $178,000 |
| Undrawn line request | About $75,000 |
| Forecast condition | Lowest weekly closing cash above zero without a draw |
Using the displayed rounded daily figure, 30 x $5,918 is approximately $177,540. Using the unrounded annual expense divided by 365 gives approximately $177,534. Both support the same rounded $178,000 target.
The assumed line request combines the original $27,000 forecast trough with one $46,000 payroll, rounded to about $75,000. Apply while the financial statements and cash position are strong, and treat approval as uncertain. The line is a backstop for a forecast miss or an early shortfall; the cash reserve also has to serve the other shocks in a business risk and resilience plan.
SBA-backed lines to discuss with a lender
The SBA does not provide 7(a) loans directly; you apply through a lender, which decides whether to lend, and the SBA guarantees part of an eligible loan. Ask the lender which product fits the use of funds and what documentation it requires.
| Program | Published features relevant to a line |
|---|---|
| SBA Express | Up to $500,000, with a maximum SBA guarantee of 50%; revolving lines can run up to 10 years |
| Seasonal CAPLine | Finances seasonal increases in receivables, inventory or associated labor |
| 7(a) Working Capital Pilot | Monitored lines up to $5,000,000, with a maximum maturity of 60 months; the SBA suggests it for businesses with at least one year of operating history that can produce timely financial statements and aging reports |
The SBA describes Express and Seasonal CAPLine among its 7(a) loan types. Fernhollow's assumed seasonality makes the Seasonal CAPLine a question for a lender, not an assurance that the company qualifies. The Working Capital Pilot's reporting requirements make an accurate receivables aging and timely financial statements relevant before an application.
Credit is not guaranteed. In the Federal Reserve's 2026 Report on Employer Firms, 42% of firms that applied for financing received the full amount they sought, 36% received some or most, and 22% received none. The 2025 survey had 6,525 responses from a convenience sample of employer firms with 1 to 499 employees; it was not a random sample.
The survey was fielded from September 3 through November 14, 2025. Rising costs of goods, services or wages were the most common financial challenge, and 77% reported rising costs, tariff-related costs, or both. Those pressures make it useful to test a forecast against higher expected payments while there is still time to adjust.
Stage 7: The fixed forecast and funded reserve
The after forecast keeps Fernhollow's assumed $38,000 opening balance and places the $24,000 payables timing release in weeks 1 and 2. It adds the assumed $176,000 receivables release evenly across weeks 3 through 13. Subscription savings are left out of the table because they are too small to change any displayed week.
| Week | Opening | Receipts | Payroll | Materials | Other out | Net | Closing |
|---|---|---|---|---|---|---|---|
| 1 | 38,000 | 41,000 | 46,000 | 2,000 | 6,000 | -13,000 | 25,000 |
| 2 | 25,000 | 38,000 | 0 | 0 | 22,000 | 16,000 | 41,000 |
| 3 | 41,000 | 60,000 | 46,000 | 13,000 | 5,000 | -4,000 | 37,000 |
| 4 | 37,000 | 52,000 | 0 | 12,000 | 6,000 | 34,000 | 71,000 |
| 5 | 71,000 | 56,000 | 46,000 | 12,000 | 24,000 | -26,000 | 45,000 |
| 6 | 45,000 | 51,000 | 0 | 11,000 | 5,000 | 35,000 | 80,000 |
| 7 | 80,000 | 63,000 | 46,000 | 12,000 | 6,000 | -1,000 | 79,000 |
| 8 | 79,000 | 68,000 | 0 | 12,000 | 22,000 | 34,000 | 113,000 |
| 9 | 113,000 | 66,000 | 46,000 | 11,000 | 5,000 | 4,000 | 117,000 |
| 10 | 117,000 | 71,000 | 0 | 11,000 | 6,000 | 54,000 | 171,000 |
| 11 | 171,000 | 70,000 | 46,000 | 10,000 | 22,000 | -8,000 | 163,000 |
| 12 | 163,000 | 74,000 | 0 | 10,000 | 5,000 | 59,000 | 222,000 |
| 13 | 222,000 | 72,000 | 46,000 | 9,000 | 6,000 | 11,000 | 233,000 |
| Assumed Fernhollow measure | Before | After |
|---|---|---|
| DSO | 58 days | 36 days |
| DPO | 15 days | 30 days |
| DIO | 12 days | 12 days |
| Cash conversion cycle | 55 days | 18 days |
| Days cash on hand | 6.4 days | 39.4 days |
| Weeks closing below zero | 7 | 0 |
| Week 13 closing cash | $33,000 | $233,000 |
The after forecast's lowest closing balance is $25,000 in week 1, before the receivables fixes take effect. That thin early balance is where the proposed line provides a backstop if a receipt arrives late or an expense exceeds the assumption. The model does not assume a line draw.
At week 13, assumed cash reaches $233,000, above the approximately $178,000 reserve target. The after cash conversion cycle is 12 + 36 - 30 = 18 days, with inventory timing unchanged. These are forecast results: confirm deposits, actual settlement dates and supplier due dates before treating the projected reserve as available cash.
A weekly cash review with observable checks
- Reconcile the opening balance. Match week 1 opening cash to the bank balance and identify deposits or payments still in transit.
- Review the receivables aging. Give every material open invoice an expected payment date and check that it appears in the matching forecast week.
- Check completed jobs. Confirm each job marked complete has an invoice, a due date and any deposit credited against the balance.
- Check outgoing payments. Match payroll and supplier payments to their actual due dates, including bills shifted by the payables change.
- Compare actuals with the prior forecast. Record each receipt and disbursement variance by line, then correct the remaining assumptions.
- Roll the forecast forward. Drop the finished week, add a new week 13 and record the lowest projected closing balance alongside the cash reserve and any available undrawn line.

Put your next steps in order
Build on what you have just read with a free ebook on semantic SEO and AI visibility. Get worked examples, decision rules, checklists and a do-this-week action in every chapter, plus a six-week plan for your site.