How to Prepare a Business for Sale

On this page
Business
A sellable business produces its results, its records, and its customer relationships without the owner, and can prove that to a stranger. How to prepare a business for sale starts with making those things independently verifiable: remove the owner from the critical path, document the work, limit customer concentration, clean the books, and put IP and accounts in the company's name. Those same changes make a business more valuable to keep because they lower the risk the owner carries and free the owner's time. In Q2 2026, BizBuySell reported an average cash flow multiple of 2.7 and a median sale price of $349,250 across 2,117 closed sales.
How to read the annual sellability standard
Iron Goo's standard asks whether a company could put credible evidence in front of a buyer next quarter. Run it once a year, even when a sale is nowhere on the calendar. A company of 10 to 200 people can use the same tests; the number of processes, contracts, and accounts will differ.
MUST items are gates. A failed gate gives a buyer a material problem to find during diligence, even if the rest of the business looks attractive. SHOULD items can raise the quality of earnings or make a deal easier to complete, while AVOID items describe habits or gaps that can destroy value.
This is general information, not financial, tax, or legal advice. Ask an accountant, broker, or attorney to assess your own circumstances.
How small businesses are valued: SDE, EBITDA, and the multiple
A common starting point for a small business price is an earnings figure multiplied by a multiple. Both parts need scrutiny: the buyer has to accept the earnings, and the multiple has to fit that particular earnings measure and business. Revenue can help describe scale, but it does not show how much earnings remain after the work is done.
Seller's discretionary earnings, or SDE, starts with pre-tax profit and adds interest, depreciation and amortization, one working owner's salary and benefits, owner perks, and genuinely one-time costs. Each proposed add-back needs an explanation and evidence. A buyer may disagree that an expense was personal or unlikely to recur.
SDE = pre-tax profit + interest + depreciation and amortization + one working owner's salary and benefits + owner perks + genuinely one-time costs
For an owner-operator business, SDE shows the earnings available before paying a replacement for that owner. In this simplified bridge, adjusted EBITDA is SDE minus a market-rate salary for a manager to replace the owner. Actual adjustments depend on the business and the buyer's analysis.
BizBuySell's explanation of SDE and EBITDA says SDE is generally more relevant to smaller owner-operator businesses, while EBITDA may be more relevant to larger companies with management teams. It also says an SDE multiple is typically smaller than an EBITDA multiple and warns against applying either multiple to the other earnings figure.
Brightwater's earnings bridge
Brightwater Facility Services is an openly hypothetical 18-person commercial cleaning company. Assume the following trailing 12-month figures, including a $130,000 market-rate salary for a general manager who would replace the working owner. The owner salary, vehicle expense, and legal fee are proposed add-backs, subject to a buyer's review.
| Earnings component | Assumed amount |
|---|---|
| Pre-tax profit | $260,000 |
| Interest | $15,000 |
| Depreciation | $45,000 |
| One working owner's salary | $90,000 |
| Owner's personal vehicle expense | $12,000 |
| One-time legal fee for a settled dispute | $20,000 |
| SDE | $442,000 |
| Market-rate replacement manager salary | ($130,000) |
| Adjusted EBITDA | $312,000 |
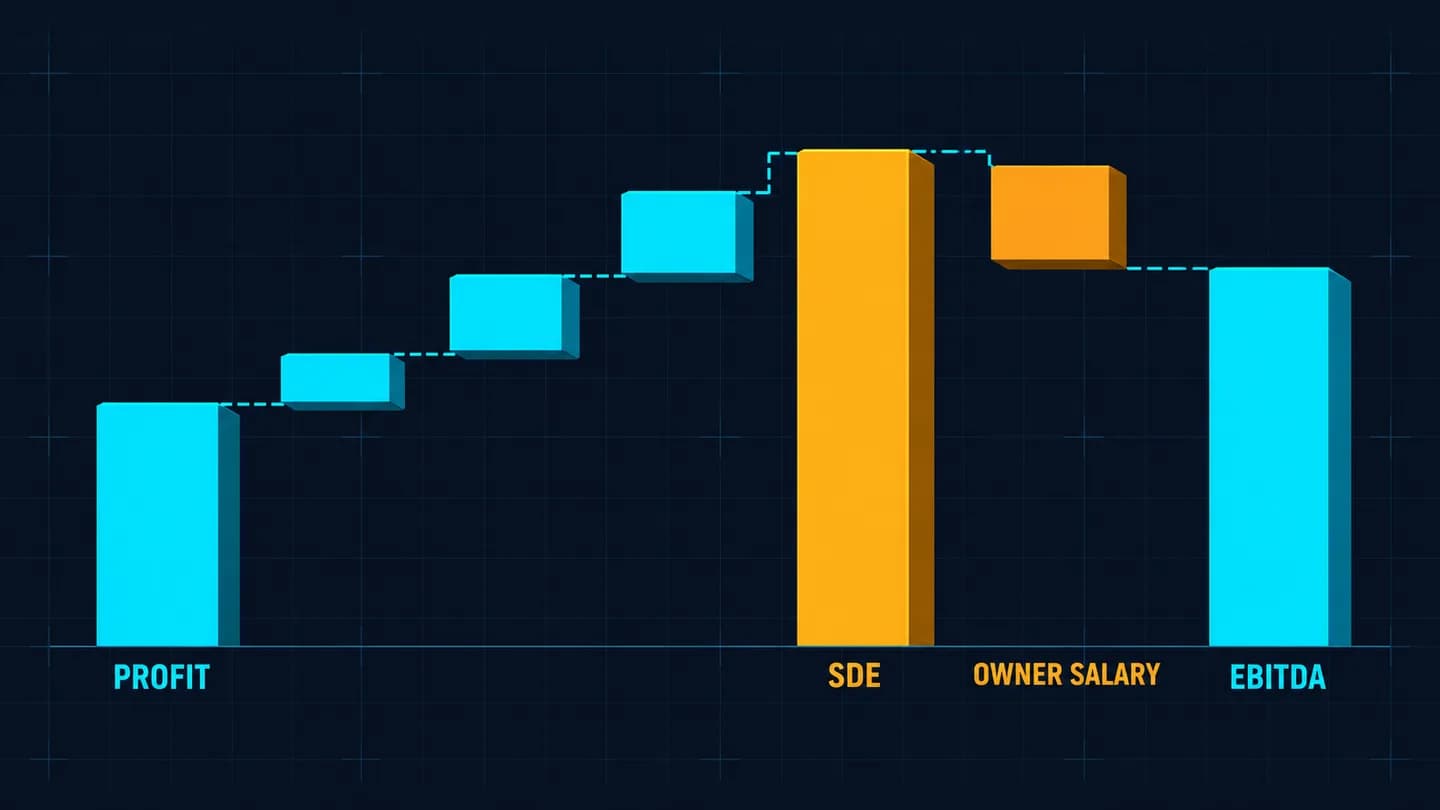
Owner pay and other accepted adjustments lift profit to SDE. The assumed cost of a manager who replaces the owner then reduces that figure to adjusted EBITDA.
The replacement salary makes owner dependence visible in the earnings figure a buyer prices. Brightwater's assumed $90,000 owner salary is added back to SDE, but a buyer who needs a $130,000 manager cannot treat that owner's work as free. The two figures answer different questions, so applying an SDE multiple to the $312,000 EBITDA would mix the measures.
The BizBuySell Q2 2026 Insight Report reported 2,117 closed sales, a 2.7 average cash flow multiple, and a $349,250 median sale price. The transactions are voluntarily reported by brokers and cover small businesses; a company with 10 to 200 people may be above the median. The report does not define its cash flow multiple on that page. Our reading, based on BizBuySell's description of listing cash flow as normalized SDE or sometimes normalized EBITDA, is that it is an SDE-style measure.
The average is a market observation, not a multiple assigned to Brightwater or your company. The Q3 2026 Insight Report release, published October 20, 2026, reported 2,132 sales and a $350,000 median sale price. It said average cash flow multiples rose 2.6% but gave no absolute multiple.
What a rejected add-back does to the arithmetic
Suppose a buyer decides Brightwater's $20,000 legal fee is likely to recur and rejects that add-back. At 2.7, the calculation changes from $442,000 × 2.7 = $1,193,400 to $422,000 × 2.7 = $1,139,400. The difference is $54,000, or $20,000 × 2.7.
That is arithmetic only, not a valuation. It holds the multiple fixed to show the effect of one disputed input; an actual buyer may use another earnings figure, multiple, or adjustment.
MUST: evidence a buyer can verify
M1. The company works through a two-week owner absence
Reason. A buyer needs to know which results depend on the owner personally. If approvals, customer calls, or access to a critical system stop when the owner is away, a replacement has work to absorb before the business can perform independently.
Test. Our rule of thumb is a two-working-week absence with the owner's phone off. Use the calendar and a shared log to record every decision, approval, login, and customer call that waits. For each waiting item, name one Accountable person and a backup; check that the backup has access, instructions, and time, as described in the organization and roles guide.
Pass line. No revenue-affecting item waits for the owner, and every waiting item has one named Accountable person and a backup who can handle it. If routine steps still wait on one person, Iron Goo's operations service follows an audit, build, operate approach, including chatbots for repeat inbound questions and an agentic operations layer for internal operations work with scoped credentials and audit logging.
A planned absence is a test, not permission to leave customers without cover. Assign the people and access first, then record what still comes back to the owner. A long list is useful evidence: each entry names a dependency that can be fixed and tested again.
M2. A new person can run documented processes
Reason. A buyer cannot inspect a process that exists only in someone's memory. A list of document titles is also insufficient if the instructions are outdated or nobody can use them.
Test. Open the SOP index and check that each revenue-critical process has an ID, revision, effective date, named Accountable owner, and review date. Give a person who has not performed the work the current instructions and observe whether they can complete it; the SOP guide sets out how to write the SOP and run the new hire test.
Pass line. Every revenue-critical process appears in the index with a current revision, and another person completes each tested process from its instructions. Record failures and retest after the owner of the SOP corrects them.
M3. The books reconcile and add-backs have evidence
Reason. A buyer prices earnings and then checks the records behind them. Personal spending mixed into operating costs and unexplained adjustments make Brightwater's $442,000 SDE harder to accept, even when the underlying work is sound.
Test. In the accounting system, open each monthly profit and loss statement and reconcile its underlying transactions to the bank statements. Separate personal costs, prepare an add-back schedule with receipts and explanations, and place three years of financial statements and tax returns in the diligence folder. For Brightwater, the schedule would identify the $12,000 vehicle expense and $20,000 legal fee separately, with evidence supporting each proposed adjustment.
Pass line. Monthly records reconcile, personal costs are identifiable, each proposed add-back has supporting evidence, and three years of statements and returns are ready to inspect. Buyers commonly ask for those three years; that request is separate from tax retention rules.
The IRS record-retention guidance gives a default period of three years, with six years for unreported income exceeding 25% of gross income shown on the return and seven years for a worthless securities or bad debt deduction claim. Employment tax records must be kept for at least four years after the tax becomes due or is paid, whichever is later. These are tax rules, not sale rules.
Clean historical books sit beside a forward-looking cash plan. Use the cash and financial resilience guide for the 13-week cash forecast and reserve.
M4. No customer exceeds about 25% of revenue
Reason. A buyer who depends on one customer for a large share of revenue has to consider what happens if that customer leaves or renegotiates. The exposure remains an operating risk while you own the company.
Test. Export trailing 12-month revenue by customer from the accounting system. Divide the largest customer's revenue by total revenue, using the same client concentration metric and the 25% line, which is our rule of thumb. Brightwater's assumed largest customer accounts for $744,000 of $2,400,000, or 31.0%, so it fails; its second-largest account is $264,000, or 11.0%.
Pass line. No customer accounts for more than about 25% of trailing 12-month revenue. If the largest account exceeds the line, put new-business development on the weekly list and monitor the percentage as revenue changes; the risk and resilience guide treats concentration and key-person dependence as operating exposures.
Do not mistake a lower percentage caused by a shrinking large account for progress by itself. Keep the numerator and total revenue beside the percentage so the owner can see what changed. A buyer will want to inspect the customer relationship and its agreement as well as the calculation.
M5. The company can show what IP and data it owns
Reason. Paying for a website, logo, code, or copy does not by itself prove that the company owns the copyright. A buyer needs a chain of documents showing what rights the company has and what can transfer.
Test. Make a spreadsheet of every contractor and agency that produced code, a site, brand assets, content, data models, or automations. For each deliverable, find the signed assignment clause and save it with the agreement; also identify company data, where it is held, and the contracts governing access and transfer.
Pass line. Every contractor row has a signed assignment for the relevant work, and the company can identify its data and the documents governing its rights. Flag exceptions for review before describing an asset as company-owned.
Copyright Office Circular 30 describes two work-made-for-hire routes. Work prepared by an employee within the scope of employment qualifies; specially ordered or commissioned work must fall within one of nine statutory categories and be covered by a written instrument signed by both parties. In our general reading of those rules, custom software, websites, logos, and copy made by independent contractors usually need a signed assignment to transfer copyright; a work-for-hire label alone may not settle ownership.
17 U.S.C. 204(a) states: “A transfer of copyright ownership, other than by operation of law, is not valid unless an instrument of conveyance, or a note or memorandum of the transfer, is in writing and signed by the owner of the rights conveyed or such owner's duly authorized agent.” Find the signed instrument covering the actual rights and deliverables. An invoice does not transfer ownership.
In our reading, a seller cannot promise copyright exclusivity over AI output that is not copyrightable. Keep an AI-content log identifying what was generated and what people selected, arranged, or changed, so a buyer can assess the human contributions and the rights being offered.
The Copyright Office's Part 2 report, published January 29, 2025, states: “The use of AI tools to assist rather than stand in for human creativity does not affect the availability of copyright protection for the output.” It also states: “Copyright does not extend to purely AI-generated material, or material where there is insufficient human control over the expressive elements.”
The report adds: “Based on the functioning of current generally available technology, prompts do not alone provide sufficient control.” It calls for a case-by-case assessment and recognizes protection for human creative selection, coordination, arrangement, and modification where the requirements for authorship are met. Keep source files and revision records alongside the log so those contributions can be inspected.
The Copyright Office registration guidance, effective March 16, 2023, requires applicants to disclose AI-generated content and briefly explain the human author's contributions. AI-generated content that is more than de minimis should be excluded from the registration application. The Supreme Court denied certiorari in Thaler v. Perlmutter (No. 25-449) on March 2, 2026, leaving in place the D.C. Circuit's March 2025 decision upholding the human authorship requirement.
SHOULD: improve earnings quality and transfer readiness
S1. Show the quality of recurring revenue
Reason. A repeat customer and a contracted customer do not provide the same evidence of future revenue. A buyer also needs to see whether recurring work produces an acceptable contribution after its direct costs.
Test. Export 36 months of customer revenue and classify it as contracted, repeat without a contract, or one-off. Record renewal dates and churn alongside the split, then use the pricing and unit economics guide to check contribution by customer or product line. For Brightwater, show which cleaning accounts have signed recurring agreements and which simply order again.
Pass line. The 36-month split reconciles to the accounting records, renewal and churn are visible, and contribution is available for each material customer or product line. A buyer can trace a category total back to the underlying invoices and agreements.
In the Q2 2026 Insight Report, broker Jason Ward said: “Qualified buyers remain active, particularly for businesses with strong financial performance, recurring revenue, and experienced management.” Contracted revenue still needs inspection: a short cancellation provision or a pending renewal changes what the buyer can reasonably expect.
S2. Identify contracts that need consent to transfer
Reason. A contract can be valuable to the current company and still contain restrictions that affect a sale. An anti-assignment clause generally restricts transfer of the agreement, often requiring the other party's consent; a change-of-control clause may give rights or impose conditions when ownership changes.
Test. Add columns to the contracts register for counterparty, agreement, expiration, anti-assignment language, change-of-control language, required consent, and status. Check customer agreements, leases, supplier contracts, software licenses, and other material agreements against the actual documents, then have counsel read the clauses and identify the required steps.
Pass line. Every material agreement is in the register, its relevant clauses and consent status are recorded, and counsel has reviewed the contracts that could affect a transaction. A blank field means the agreement still needs review.
In an asset sale, contracts may need to be assigned to the buyer, making assignment restrictions relevant. In a stock sale, the company remains the contracting party, but change-of-control provisions may still apply; the actual wording and transaction structure govern the analysis.
S3. Give each key person a backup and a retention plan
Reason. Owner independence does not solve a dependency on an operations manager, estimator, or account lead. A buyer will ask whether revenue can continue if a person essential to delivery or sales leaves during a transition.
Test. Our rule of thumb defines a key person as anyone whose departure would stop a revenue process for more than two weeks. List those people in a spreadsheet, link each to a documented process, name a trained backup, and record a retention arrangement such as a stay bonus payable after a transition period.
Pass line. Each person who meets the rule has a documented process, a backup who has been trained to perform it, and a recorded retention arrangement. Check the backup's actual access and available time before marking the row complete.
S4. Put critical accounts in the company's name
Reason. Control of an account can determine who can maintain a domain, receive customer payments, or operate software. A buyer needs to identify the account owner and the people who can administer it.
Test. Open the admin consoles and account records for the domain registrar, email administration, payment processor, bank, advertising accounts, AI tool subscriptions, and API keys. Record the registered owner, named administrators, and the business owner for each AI tool; check that access and billing details match the company's records.
Pass line. The company is the registered owner of each critical account, and two named people have appropriate administrative access to each, our rule of thumb. The AI tool register identifies a named business owner for every tool, and the access list is current.
Two administrators should be identifiable people whose access is maintained, not a shared login whose password nobody can trace. Where an account has role restrictions, record the available access and the steps needed to transfer control.
AVOID: gaps that weaken a sale
A1. Personal spending without an add-back schedule
Reason. A buyer cannot reliably distinguish owner benefits from operating costs when the transactions and evidence are mixed together. An unsupported add-back can reduce the earnings the buyer accepts.
Test. Filter the accounting system for personal expenses and compare each transaction with the add-back schedule and receipt. Flag any item without an amount, date, explanation, and supporting record.
A2. Handshake deals with the largest customers
Reason. A long customer relationship has value, but an unsigned understanding leaves the buyer with less evidence about scope, pricing, renewal, and termination. The exposure is sharper when the customer is a large share of revenue.
Test. Sort the trailing 12-month revenue export by customer and match the largest accounts to signed agreements in the contracts folder. Flag each material account with no written agreement and record its current pricing and renewal arrangement.
A3. Contractor-built assets with no assignment
Reason. An invoice proves payment; it does not necessarily transfer copyright. A missing assignment can leave the company unable to substantiate ownership of an asset a buyer expects to receive.
Test. Compare the contractor list with the deliverables in the product, website, brand, content, and automation folders. Flag each deliverable for which the company cannot produce a signed assignment covering the work.
A4. AI-generated assets presented as exclusive IP
Reason. A claim of exclusive copyright over output with insufficient human authorship may promise a buyer rights the seller cannot provide. The human-authored contributions need their own evidence.
Test. Review the asset inventory and AI-content log for material described as exclusive. Check whether the record identifies generated material, human changes, and the basis for the rights claim; flag unsupported claims for review.
A5. The owner as the only salesperson or signer
Reason. A single salesperson can make customer relationships difficult to transfer. A sole signer can also delay routine work whenever that person is unavailable.
Test. Review the sales pipeline, customer contacts, approval matrix, and signing authorities. Flag each revenue process or routine approval for which the owner is the only person with the relationship, access, or authority to act.
Preparation, clean financials, and minimized owner dependence are now absolute prerequisites to securing a successful close.
Due-diligence readiness checklist
A buyer should be able to open each item and trace it to an underlying record. Assign one person to maintain the folder index and record the date each item was last checked.
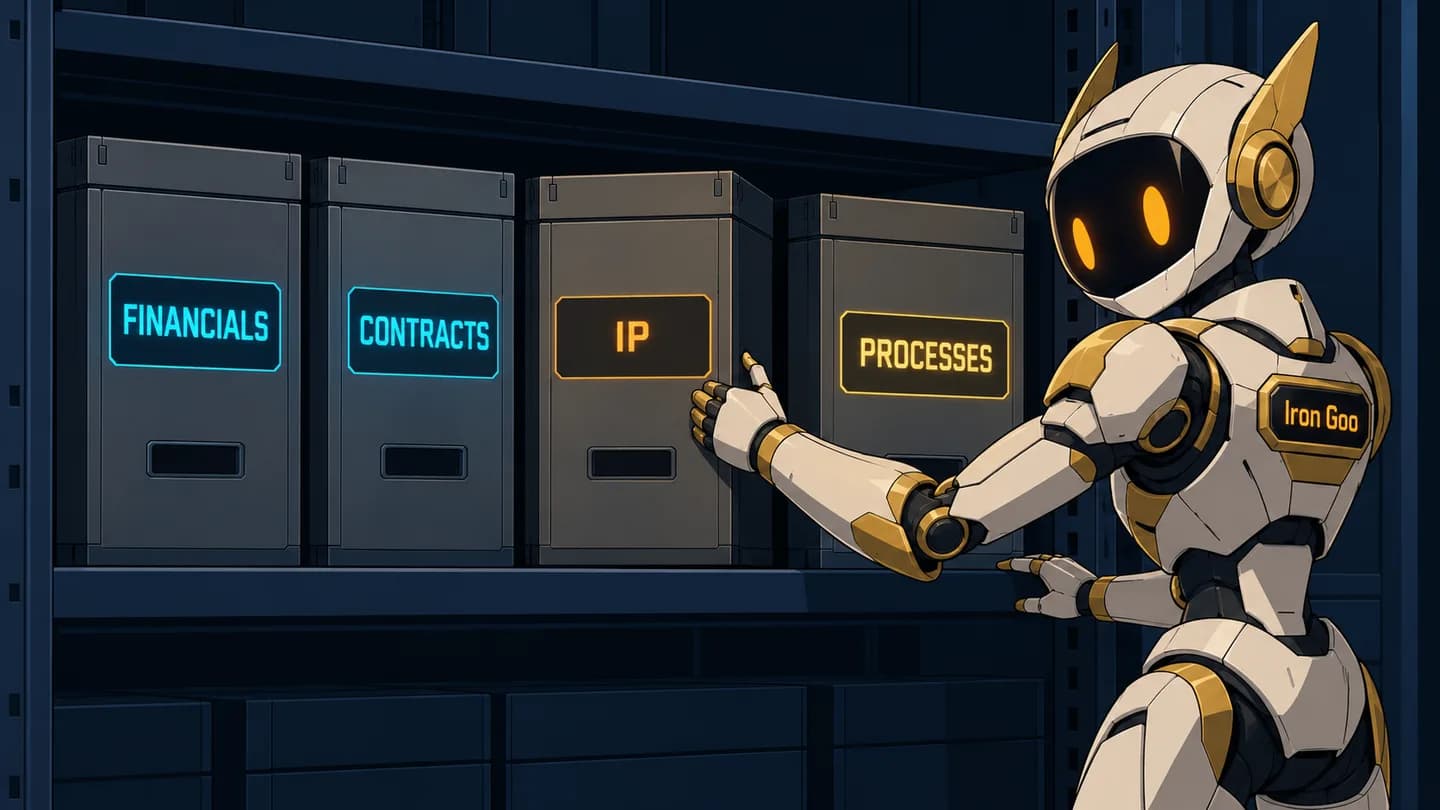
The data room holds financial, contract, operating, and IP evidence a stranger can inspect. Pay particular attention to the IP folder, where signed assignments can be missing.
- Three years of financial statements and tax returns are in the data room.
- Monthly profit and loss records reconcile to bank statements.
- The add-back schedule includes receipts and explanations for each proposed adjustment.
- Revenue by customer is available for 36 months.
- A current accounts receivable aging report is available.
- The contracts register has assignment and change-of-control columns.
- Signed IP assignments are filed for every contractor who created relevant assets.
- Employee agreements, including confidentiality and invention assignment agreements where used, are filed.
- The AI tool register and AI-content log are current.
- The SOP index includes revisions.
- The responsibility map names accountable people and backups.
- Current leases, licenses, and permits are filed.
- A litigation and claims list is available, including any open matters.
- Current insurance policies are filed.
Self-scoring table
Enter 1 when the stated pass line is met and 0 when it is not. For AVOID items, enter 1 when the test finds no such gap and 0 when it finds one; record the evidence and owner of each correction beside the table in your working copy.
| ID | Requirement | Type | How scored | Your score |
|---|---|---|---|---|
| M1 | Owner independence | MUST | 1 if the two-week absence meets the pass line; otherwise 0 | |
| M2 | Documented processes | MUST | 1 if the index and new hire tests meet the pass line; otherwise 0 | |
| M3 | Clean books | MUST | 1 if reconciliation, add-backs, and three years of records meet the pass line; otherwise 0 | |
| M4 | Customer concentration | MUST | 1 if no customer exceeds about 25% of trailing 12-month revenue; otherwise 0 | |
| M5 | IP and data rights | MUST | 1 if assignments and data rights meet the pass line; otherwise 0 | |
| S1 | Recurring revenue quality | SHOULD | 1 if the revenue split, renewal, churn, and contribution meet the pass line; otherwise 0 | |
| S2 | Contracts that transfer | SHOULD | 1 if the register and clause review meet the pass line; otherwise 0 | |
| S3 | Key-person coverage and retention | SHOULD | 1 if every identified key person meets the pass line; otherwise 0 | |
| S4 | Company-owned accounts | SHOULD | 1 if ownership, administrators, and the AI tool register meet the pass line; otherwise 0 | |
| A1 | Undocumented personal spending | AVOID | 1 if the test finds no undocumented personal spending; otherwise 0 | |
| A2 | Handshake deals with largest customers | AVOID | 1 if the test finds no material account without a written agreement; otherwise 0 | |
| A3 | Contractor assets without assignment | AVOID | 1 if the test finds no relevant deliverable without a signed assignment; otherwise 0 | |
| A4 | Unsupported exclusive AI IP claims | AVOID | 1 if the test finds no unsupported exclusivity claim; otherwise 0 | |
| A5 | Owner as only salesperson or signer | AVOID | 1 if the test finds no owner-only revenue process or routine approval; otherwise 0 |

Put your next steps in order
Build on what you have just read with a free ebook on semantic SEO and AI visibility. Get worked examples, decision rules, checklists and a do-this-week action in every chapter, plus a six-week plan for your site.