How Much Should a Small Business Spend on Marketing?

Table of contents
- Company size changes the reported marketing budget percentage
- The mean and median give different answers to a budget meeting
- Does the SBA recommend 7 to 8 percent of revenue?
- How much do small businesses actually spend on advertising?
- Four benchmarks give one company four different dollar amounts
- Affordable acquisition cost sets the budget ceiling
A small business marketing budget averaged 16.26% of revenue among 23 companies with fewer than 50 employees in The CMO Survey, about twice Gartner's 7.8% figure for a predominantly enterprise sample. So how much should a small business spend on marketing? There is no single right percentage: the two survey figures being compared run from a 5% overall median to over 16% in the smallest employee band, and affordable customer acquisition cost should decide your budget.
The distinction between those figures matters before you put a percentage into a spreadsheet. A median across companies of different sizes and a mean for a small employee band describe different groups. Neither tells you what your company can afford to pay for its next customer.
The CMO Survey, sponsored by Duke University's Fuqua School of Business, Deloitte, and the American Marketing Association, was fielded from 7 to 29 January 2026 among marketing leaders at US for-profit companies: 308 of 2,111 invited leaders responded, 97% were at VP level or above, and 154 answered the revenue question.
Gartner's 2026 CMO Spend Survey reported the 7.8% average after asking 401 CMOs and marketing leaders in North America, the UK, and Europe between January and March 2026. It is useful context for enterprise budgets, but I would not use it as a target for a 40-person company.
A marketing budget buys reach in a market where buyers often research before contacting a company. The guide to what modern marketing consists of explains the work that budget can fund; the dollar amount still has to fit your economics.
Company size changes the reported marketing budget percentage
The CMO Survey's size bands show widely different average marketing expenses as a percentage of revenue. The firm and industry breakout report separates respondents by employee count and by revenue, giving a 10 to 200-person company two ways to find a comparison group.
| Company size measure | Band | Mean marketing expenses as % of revenue | Answers |
|---|---|---|---|
| Employees | Under 50 | 16.26% | 23 |
| Employees | 50 to 99 | 13.31% | 19 |
| Employees | 100 to 499 | 8.80% | 30 |
| Employees | 500 to 999 | 5.48% | 18 |
| Annual revenue | Under $10 million | 13.34% | 20 |
| Annual revenue | $10 million to $25 million | 17.40% | 15 |
| Annual revenue | $26 million to $99 million | 11.14% | 18 |
| Annual revenue | $100 million to $499 million | 5.86% | 34 |
The employee and revenue bands are two views of the survey, so a company may fit one row in each group. For a company with 80 employees and $8 million in revenue, the corresponding means are 13.31% and 13.34%. Those are useful starting points for a budget conversation, not independent votes for an allocation.
The under-50 figure deserves particular caution. The standard deviation is 13.43 percentage points, and our calculation of a 95% interval using the survey's own normal approximation is about 10.8% to 21.7%: 16.26 plus or minus 1.96 times 13.43 divided by the square root of 23. With only 23 answers and skewed data, the real uncertainty is wider.
The sample also comes from companies whose responding marketing leaders were overwhelmingly VP-level or above. It is a reasonable reading that a 15-person company often lacks such a leader, so the under-50 group may not resemble the full population of very small businesses. Treat 16.26% as a reported result from 23 answers, not a spending instruction.
The CMO Survey's sector figures vary too: B2B product companies reported 7.02% of revenue, B2B services 10.07%, B2C product 11.99%, and B2C services 7.24%. A 40-person B2B services company can compare itself with both the under-50 employee band and the B2B services group, while remembering that neither is a custom quote for its circumstances.
The mean and median give different answers to a budget meeting
The CMO Survey's 8.96% mean sits well above its 5% median, and its highest reported answer was 42.99% of revenue. A few heavy spenders pull the average up, while half of the companies answering the question spend 5% or less.
That gap changes how you should use the word “average” in a budget meeting. If someone proposes 9% because it resembles the survey mean, ask why the company should spend above the level reported by at least half the respondents. The answer might be a credible growth target and affordable acquisition costs, but the mean alone does not supply either.
The median is also an overall figure, not a median calculated for companies under 50 employees. A smaller company should read the 5% and 16.26% figures together with their labels attached. They describe different slices of a survey whose respondents are not a random cross-section of every small business.
Does the SBA recommend 7 to 8 percent of revenue?
The SBA pages reviewed do not recommend spending 7% to 8% of revenue on marketing. The attribution appears on many sites without an SBA source, while the SBA's own blog gives a different answer:
SBA blog, 9 July 2019: "There's no hard and fast answer to how much your marketing budget should be."
The SBA blog post quotes third-party averages: Web Strategies reported 7.9% of revenue for marketing in 2018, and Small Business Trends reported 1.08% of revenue for advertising. Those are separate figures from outside sources, not an SBA prescription for a company's budget.
The SBA business guide's marketing section asks owners to set goals and an action plan; it gives no percentage. If someone presents 7% to 8% as an SBA rule, ask for the SBA page and the population behind the figure. A number repeated on a dozen pages still needs a source.
How much do small businesses actually spend on advertising?
Corporations with $1 to under $500,000 in assets reported advertising deductions equal to about 1.13% of business receipts for tax year 2023, according to our division of IRS totals. The same calculation gives about 1.10% for corporations with $500,000 to under $1 million in assets and 1.01% for those with $1 million to under $5 million.
The IRS Statistics of Income Table 2.1 estimates results from samples of active corporation returns. Our division of its totals for all corporations gives about 1.2%: $487.2 billion in advertising deductions divided by $40.46 trillion in business receipts. That overall figure is dominated by corporations with $2.5 billion or more in assets, which account for 55% of receipts.
An asset band is not an employee band or a revenue band. A 40-person company should check its balance sheet before choosing an asset group for comparison. The figures also describe corporations, so they do not measure spending by sole proprietors.
The numerator is the advertising deduction only, not total marketing spend. Marketing costs can also include people, agencies and tools, while The CMO Survey figures describe broader marketing expenses. Before comparing percentages, check which expenses each figure includes.
Four benchmarks give one company four different dollar amounts
A hypothetical 40-person B2B services company with $6,000,000 in annual revenue gets four very different amounts when it applies the published figures. Assume for the IRS comparison that the company falls in the $1 million to under $5 million asset band.
- The CMO Survey under-50 mean of 16.26% gives $975,600 in marketing expenses.
- Gartner's enterprise average of 7.8% gives $468,000 in marketing expenses.
- The CMO Survey overall median of 5% gives $300,000 in marketing expenses.
- The IRS asset-band advertising ratio of approximately 1.01% gives about $60,600 in paid advertising.
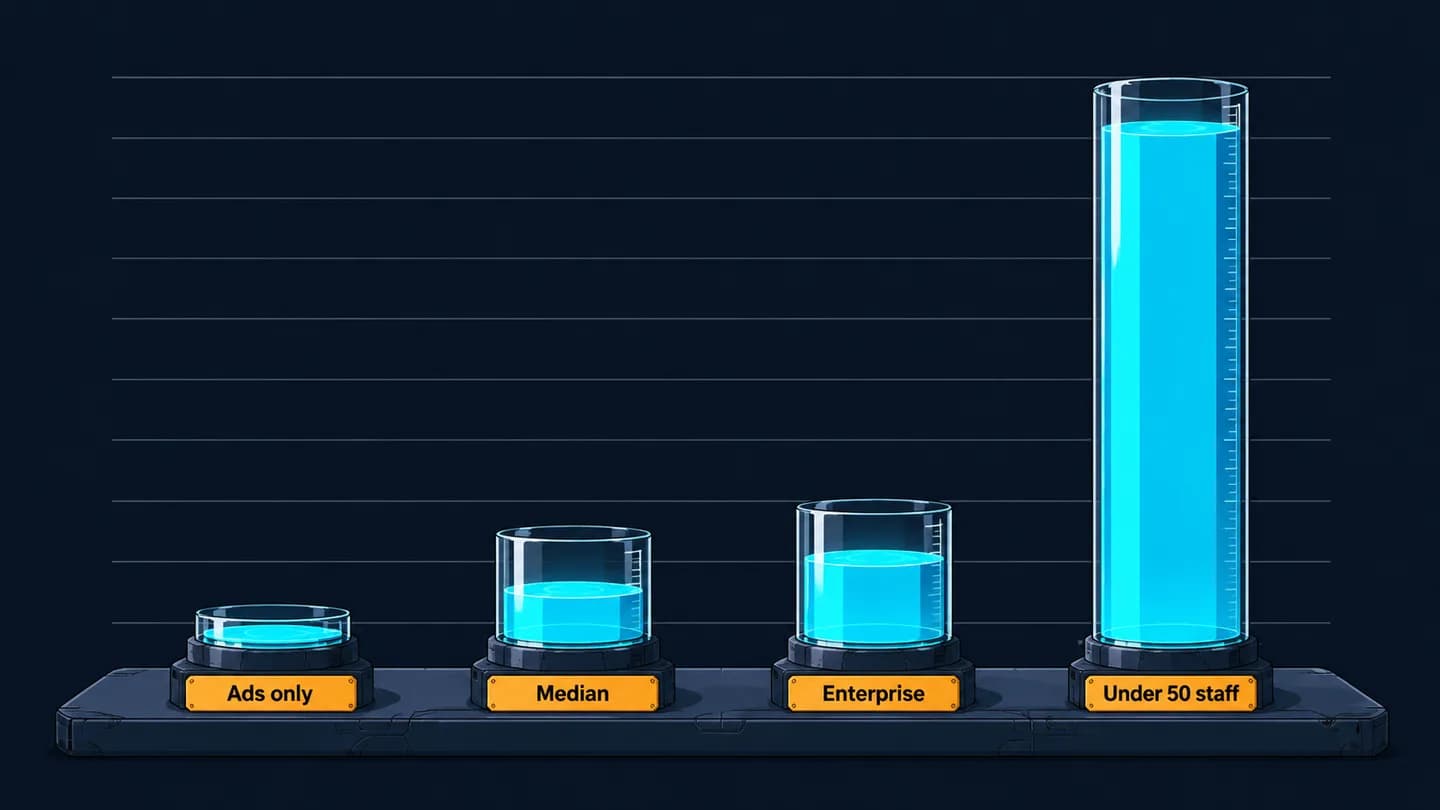
The four benchmarks produce amounts that differ by a factor of about 16. The IRS amount represents paid advertising, while the survey figures represent broader marketing expenses.
The largest amount divided by the smallest is about 16. That spread does not mean any one of the four is the correct budget: the figures describe different populations, and the IRS advertising line measures a narrower expense.
For this company, the B2B services mean offers another comparison, but it still cannot reveal how many customers the company needs or what each customer contributes after delivery costs. Those inputs determine whether a proposed budget can pay for itself on the company's chosen schedule.
Affordable acquisition cost sets the budget ceiling
Affordable customer acquisition cost gives a company a ceiling for acquisition spending based on the customers it needs and the gross margin those customers produce. The formula assumes first-year revenue and gross margin accrue evenly over the first 12 months. For a payback period of up to 12 months, the ceiling uses the share of that margin earned within the selected payback window.
acquisition_budget_ceiling = new_customers_needed x first_year_revenue_per_customer x gross_margin x (payback_months / 12)
For the hypothetical $6,000,000 B2B services company, assume each new client produces $30,000 in first-year revenue at a 40% gross margin. That gives $12,000 in first-year gross margin per client. With a stated 12-month payback target, the maximum acquisition cost is $12,000 per client.
If the company needs 25 new clients, its acquisition budget ceiling is 25 times $12,000, or $300,000. That is exactly 5.0% of its $6,000,000 revenue and equals The CMO Survey median. The match follows from the hypothetical inputs; the survey did not choose the budget.
Change the assumed gross margin to 25%, and first-year gross margin falls to $7,500 per client. The ceiling for 25 clients becomes $187,500, or about 3.1% of revenue. The customer target and revenue stay the same, but the amount available to recover acquisition costs changes.
The calculation sets a ceiling for spending aimed at acquiring those customers, not automatically the total marketing budget. If the company also budgets for work serving existing customers or other marketing goals, it needs to account for those costs separately. It also needs enough cash to fund acquisition while waiting for the gross margin to arrive.
Use the first-year revenue and gross margin of the customers you want more of. If that group is unclear, start with the customer profile; for the full method of calculating acquisition cost and payback from your records, use the guide to metrics that matter.
A second hypothetical shows why the resulting percentage can differ. A 15-person home-services company has $2,000,000 in revenue, needs 600 new customers, and earns $800 per first job at a 50% gross margin. Assuming no repeat revenue and a 12-month payback, its $400 margin per customer gives an acquisition ceiling of $240,000, or 12.0% of revenue. That percentage sits inside the range between The CMO Survey's 5% overall median and 16.26% under-50 mean.
Some customers may arrive through recommendations at close to zero acquisition cost, pulling the blended cost down; AI word of mouth adds another way recommendations can reach buyers. Count those customers consistently when comparing the blended cost with the ceiling.
For a ten-minute check, divide the last 12 months of sales and marketing spending aimed at new customers by the number of new customers won. Compare that actual acquisition cost with first-year gross margin per customer, using a 12-month payback as the assumption. If acquisition cost is below the margin, the budget can rise while cost remains below the ceiling; if it is above, buying more customers at the same cost buys losses on that first-year basis.

Put your next steps in order
Build on what you have just read with a free ebook on semantic SEO and AI visibility. Get worked examples, decision rules, checklists and a do-this-week action in every chapter, plus a six-week plan for your site.